
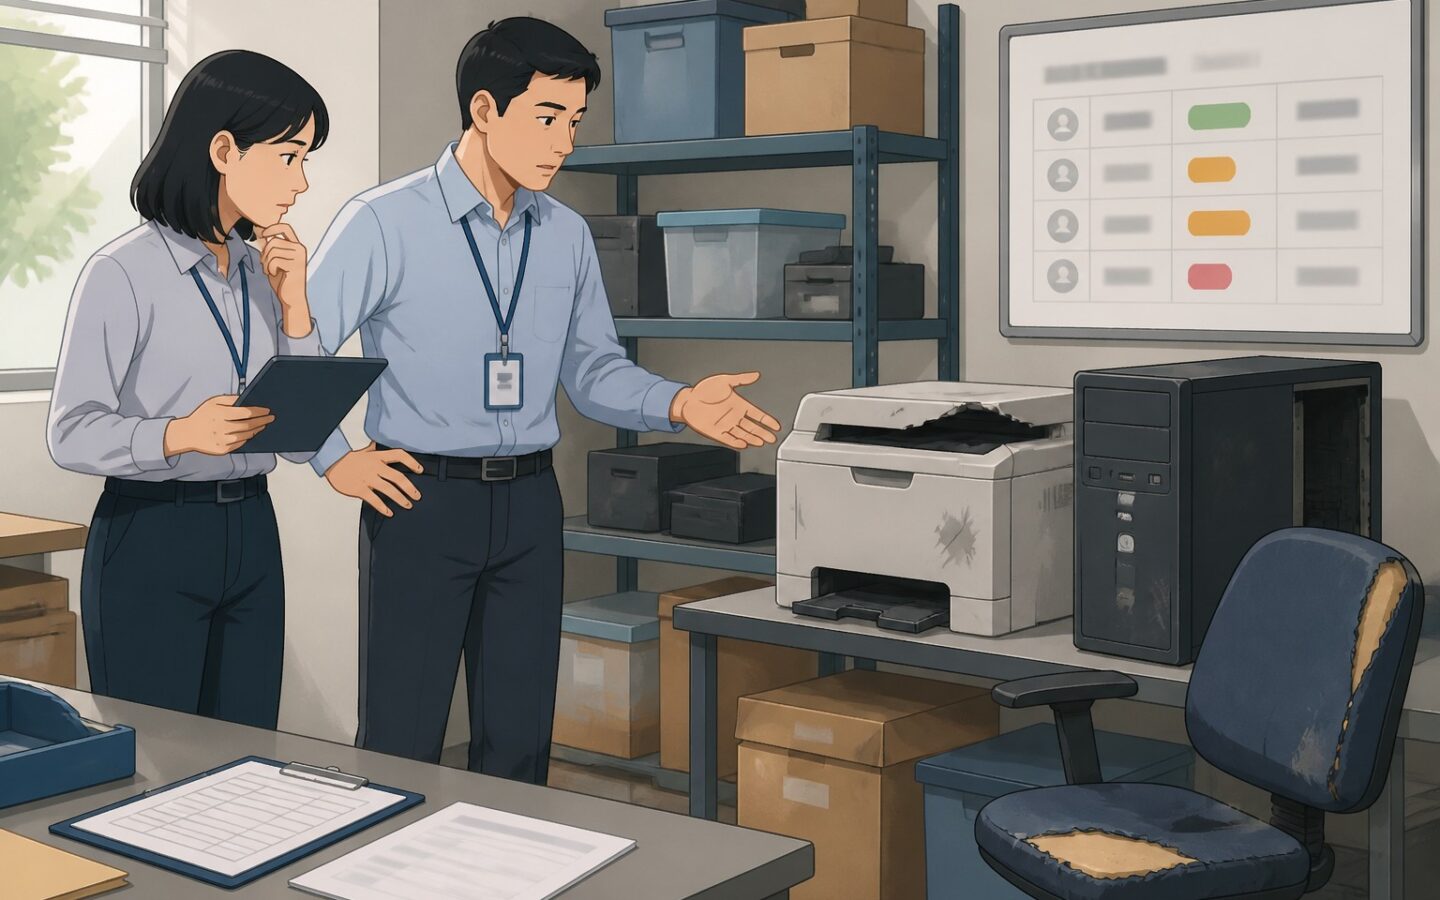
A broken printer is moved to storage, a damaged laptop is stripped for parts, and a vehicle is sold after a branch manager gives verbal approval. Months later, finance cannot explain why the assets left use, who approved the retirement, or whether the accounting entry matched the operational event. When old or damaged assets are removed inconsistently, the disposal workflow needs stronger approval checks, not just a tidier list.
A defensible fixed asset disposal process gives every retirement decision a clear trail: the reason, the reviewer, the evidence, the accounting treatment, and the final outcome. For teams in Indonesia, it also keeps tax and reporting discussions grounded in documented facts rather than memory.
The compliance point to understand first
Asset disposal is not just an administrative update. It changes the asset register, may affect depreciation, can involve proceeds or write-offs, and often requires evidence that the asset was no longer useful, safe, economical, or under the organization’s control.
The core compliance question is straightforward: if an auditor, tax reviewer, or internal management asks why an asset was removed, can the team reconstruct the decision without relying on one person’s recollection?
Common signs to watch
The first warning sign is a gap between physical reality and the fixed asset register. An asset may be broken, missing, moved to storage, or already sold, while the accounting record still shows it as active.
Another sign is inconsistent approval authority. One department may retire small equipment by email, another may use a signed memo, and a branch may rely on informal chat messages. The result is uneven evidence for decisions with similar financial consequences.
Watch for these practical symptoms:
- Assets marked as disposed without a reason code or supporting document.
- Disposal dates that do not match physical removal, sale, or scrapping dates.
- Approvals given by the same person who requested the disposal.
- No record of residual value, proceeds, or write-off assessment.
- Missing handover evidence for assets sent to vendors, buyers, or scrap handlers.
Compliance risks if ignored
Weak disposal controls can create financial reporting problems. Depreciation may continue for assets no longer in service, or stop before the disposal is properly supported. Either situation makes the asset history harder to defend.
Tax treatment in Indonesia can depend on the transaction context, documentation, and internal policy. For that reason, teams should avoid assuming that every disposal receives the same treatment. A sale, loss, destruction, donation, and internal retirement can each require different supporting files.
There is also an accountability risk. If an asset disappears from the register without a clear approval trail, the organization may struggle to separate legitimate disposal from misplacement, unauthorized sale, or weak custody control.
Practical steps for handling this topic
A good workflow does not need to be complicated, but it does need approval gates. The seven checks below create a practical sequence that finance teams, asset managers, and reviewers can apply before the record is closed.
Seven approval checks to build into the workflow
1. Disposal request completeness. The request should state the asset number, description, location, custodian, condition, proposed disposal method, and reason. If the asset number is missing, the workflow should pause until the item is matched to the register.
2. Physical verification. Someone independent from the requester should confirm that the asset exists, is in the stated condition, and matches the record. Photos, inspection notes, service reports, or damage assessments can support this step.
3. Business justification. The approver should understand why disposal is better than repair, redeployment, or continued use. For example, a laptop with repeated motherboard failure is usually easier to support than one removed only because a newer model arrived.
4. Segregation of duties. The requester, physical verifier, approver, and accounting poster should not all be the same person. Small teams may not achieve perfect separation, but they can still require at least a second reviewer for higher-value assets.
5. Financial review. Finance should check carrying amount, accumulated depreciation, possible proceeds, impairment considerations where relevant, and whether the proposed accounting entry is supported. This is where the operational event becomes a defensible accounting event.
6. Tax and documentation review. The team should prepare transaction evidence before closing the case, especially when there is a sale, compensation claim, donation, or scrap arrangement. For tax-sensitive cases, it is safer to involve a qualified tax adviser or refer to current official guidance.
7. Final register update and archive. The asset register should show disposal status, date, method, approval reference, and document location. The record should not simply disappear from active reporting without a retained historical trace.
A short implementation example
Consider a branch office in Surabaya with ten damaged office chairs, two obsolete desktops, and one photocopier that no longer works reliably. The branch requests disposal using one form, but the workflow separates the review by asset type and value.
The chairs may only need local verification and manager approval because they are low value and have no resale plan. The desktops need information technology review to confirm data removal before disposal. The photocopier needs finance review because there may be a carrying amount, service history, and possible scrap proceeds.
This approach avoids treating every item as high-risk while still keeping the reasoning visible. It also helps replacement planning because procurement can see whether retirements come from damage, age, capacity limits, or recurring repair issues.
How to apply tax controls without extra complexity
Tax controls work best when they sit inside the approval path, not after the asset has already left the premises. The goal is to capture the facts needed for later review while the people, documents, and physical evidence are still available.
Quick checklist
Before a disposal is posted, the reviewer can use a short checklist to confirm that the case file is complete. Keep it practical and tied to evidence, not lengthy policy language.
- Is the disposal method clear: sale, scrap, destruction, donation, loss, or internal retirement?
- Is there evidence of condition, such as photos, inspection notes, or repair history?
- Are proceeds, buyer details, or vendor documents recorded where applicable?
- Has finance reviewed the carrying amount and proposed accounting entry?
- Has tax sensitivity been considered for non-routine or higher-value cases?
- Is the final asset status retained in the historical record?
One useful principle is to separate active-use decisions from historical evidence. Teams that first clarify whether assets are still active can make cleaner retirement decisions later; the same logic is explained in how to distinguish active assets from older records, which also supports disposal review.
Reporting mistakes to avoid
A common reporting mistake is posting disposal based only on a disposal date, without checking when the asset actually stopped being used, when approval was granted, and when physical control changed. These dates can tell different stories.
Another mistake is recording sale proceeds without linking them to the specific asset or group of assets. If a buyer pays one amount for several items, the allocation should be documented in a reasonable way and reviewed before posting.
For Indonesia-based operations, teams should be careful with tax assumptions when transactions involve sale, compensation, intercompany arrangements, or unusual disposal methods. The safer practice is to document the facts first, then assess the treatment based on current rules and professional advice where needed.
Mistakes to avoid
Even a written disposal policy can fail if approval checks become a formality. The risk is not only that an asset is removed incorrectly, but that the organization cannot show the decision was reasonable at the time.
Frequent control breakdowns
One frequent breakdown is approving disposal after the asset has already been sold, scrapped, or thrown away. Late approval weakens the evidence because reviewers are no longer deciding; they are only accepting what already happened.
Another breakdown is using broad reason codes such as “old” or “damaged” without detail. A better note says, for example, “repair cost exceeds practical use for department needs,” “spare parts unavailable,” or “device fails security requirement after information technology assessment.”
Teams should also avoid deleting retired records from working files. A disposal should move the asset out of active reporting, but the history should remain visible for audit review, management analysis, and replacement planning.
How to respond calmly
If the current process is inconsistent, start with recent disposals instead of trying to fix years of history at once. Select a period, such as the last quarter, and review whether each disposal has request evidence, approval evidence, financial review, and final status.
Classify gaps into three simple levels. “Urgent” means the asset left the organization with weak evidence or unclear proceeds. “Monitor” means the disposal was probably valid but the file is incomplete. “Clean” means the record is supported well enough for routine review.
This classification helps the team focus without panic. Urgent cases may need follow-up documents or management explanation, while monitor cases may only need better archiving and clearer reason notes.
What to carry into tax decisions
The strongest tax and reporting position starts before the tax review. It starts when the disposal request captures what happened, who reviewed it, why the asset should be retired, and what evidence supports the conclusion.
A defensible fixed asset disposal process gives management more than compliance comfort. It shows which assets fail early, which locations request frequent replacement, and which categories produce resale value or recurring write-offs. That information can shape budgets, maintenance priorities, and procurement timing.
For each disposal, aim to preserve four things: the operational reason, the approval trail, the financial assessment, and the final disposition evidence. If those are clear, later reviews become calmer and more factual.
Use the next disposal case to test whether your approval evidence can stand on its own.
Learn more at Fisetra’s fixed asset resources.